Payment systems have always been built around one principle: a transaction happens, and the system processes it. Authorization, authentication, risk evaluation, routing, tokenization, settlement, reconciliation — each component performs a specific responsibility, and each step follows predefined rules. For decades, that model has worked remarkably well.
But transactions are no longer isolated events. A single payment can involve issuers, acquirers, networks, Token Service Providers, fraud engines, identity platforms, wallets, merchants, and processors. Failures can happen at any point. A provider can become unavailable. A token can be provisioned while a later lifecycle operation fails. And sometimes the correct action depends on what happened several steps earlier.
That raises a question worth taking seriously: what happens when payment systems need to reason about the transaction instead of simply processing it?
Payment systems execute. Agents can coordinate.
Traditional payment architecture is highly deterministic, and that determinism is essential. Payments cannot become unpredictable because we introduced AI. But not every problem in payments is deterministic.
Consider an operational exception. A provider times out. The transaction is in an uncertain state. A retry could create a duplicate. Another provider is available, the customer is waiting, and the SLA is short. A rule-based system can handle this — but as conditions multiply, the number of branches grows rapidly. An agentic layer introduces another option: let the system understand the current transaction context and determine which approved action should happen next.
A payment is becoming a journey
The biggest architectural change is treating a payment as a stateful journey rather than a request and response. The simplified lifecycle — initiated, validated, risk evaluated, routed, authorized, captured, settled — rarely holds in practice. A transaction might fail authorization, require step-up authentication, reroute, enter a pending state, trigger a fraud review, or need reconciliation later.
The question is no longer “what is the next step?” It becomes “given the complete transaction context, what is the appropriate next action?” That distinction is the heart of agentic payment orchestration.
Controlled visibility, not access
Context for an agentic payment system can include transaction state, previous attempts, merchant and customer context, risk signals, authentication status, provider availability, network response codes, token lifecycle state, SLA data, and applicable policies. The agent does not need unrestricted access to all of it. It needs the right context for the decision it is authorized to make.
The objective is not to give an AI access to the payment system. It is to give an AI controlled visibility into the payment journey.
From payment APIs to payment capabilities
Traditional integrations are API-oriented: call the authorization API, the fraud API, the tokenization API. Agentic architectures move the abstraction one level higher. Instead of exposing internal APIs, we expose controlled capabilities — authorize transaction, evaluate risk, request authentication, route payment, provision token, retry operation, initiate compensation, escalate to operations.
The agent reasons about which capability is appropriate. The underlying payment systems remain responsible for executing it. The agent decides what should happen; the payment infrastructure determines how it happens.
The agent should never become the payment authority
This is where agentic AI in payments differs from a typical AI application. A payment agent should never be able to say, “I think this transaction is safe, so approve it.” Risk decisions stay governed by explicit policies and authorized systems, and the architecture enforces the boundaries.
- The agent may select an approved route, request additional verification, retry eligible operations, classify exceptions, trigger predefined compensation flows, and escalate.
- The agent may not bypass authorization, override fraud policy, access cryptographic key material, modify financial records, change payment limits, or grant itself permissions.
Give agents decision space, not financial authority.
Exception handling is the biggest opportunity
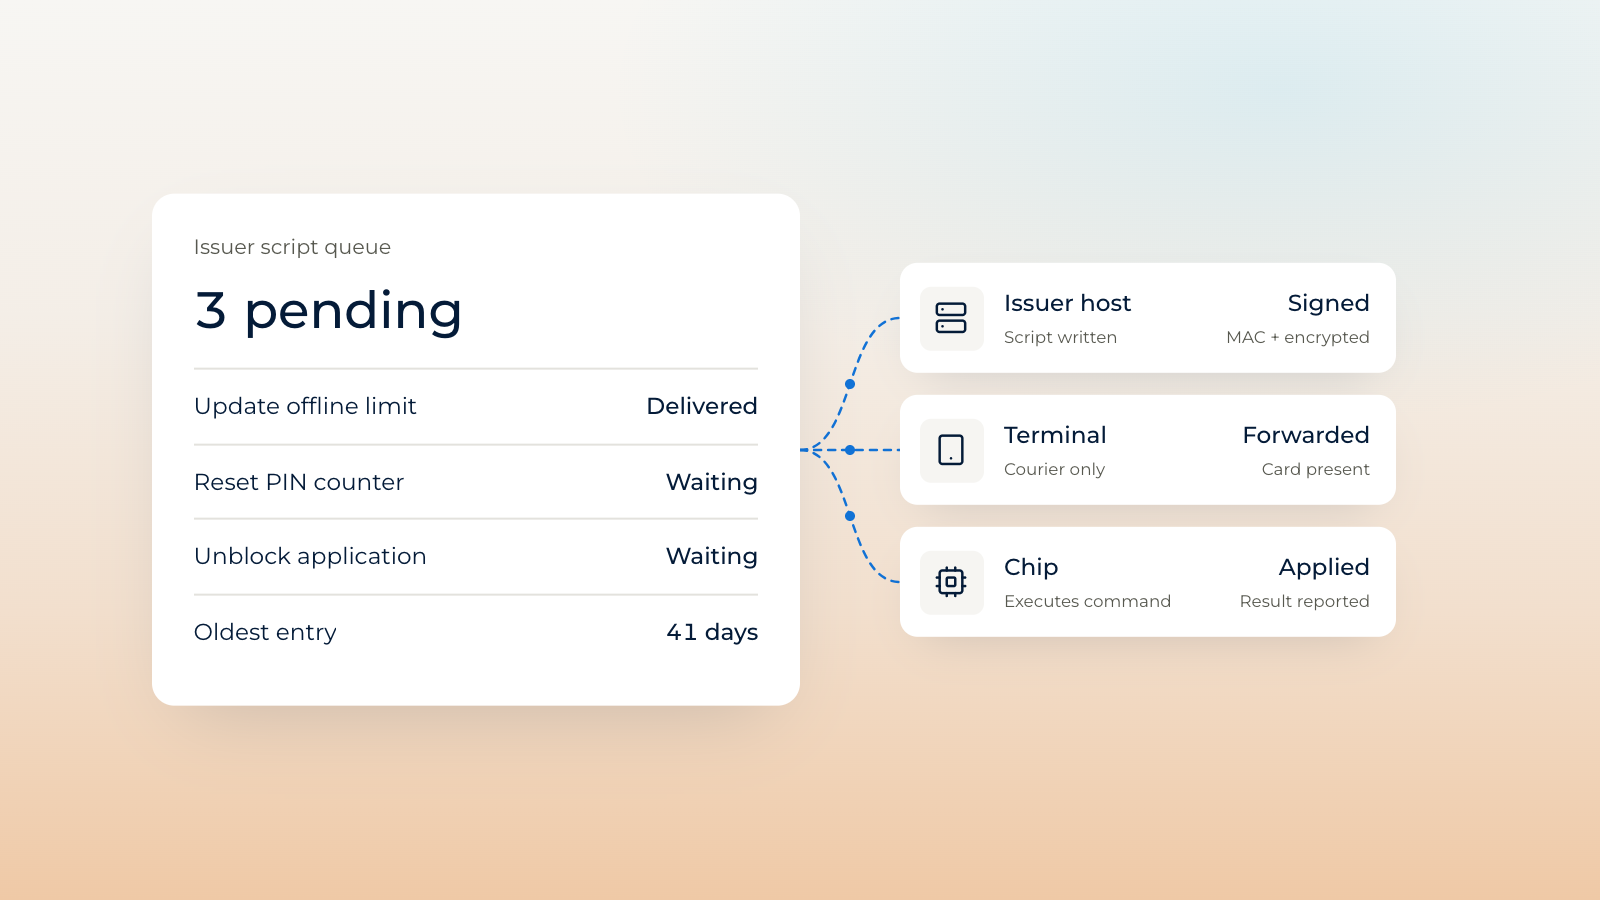
Payment infrastructure is already very good at the happy path. The harder problem is everything outside it: an ambiguous authorization response, a token provisioned but not activated, a downstream timeout, a reconciliation record that does not match. Traditional architectures answer this with more rules, more branches, more state machines — until the system becomes very difficult to reason about.
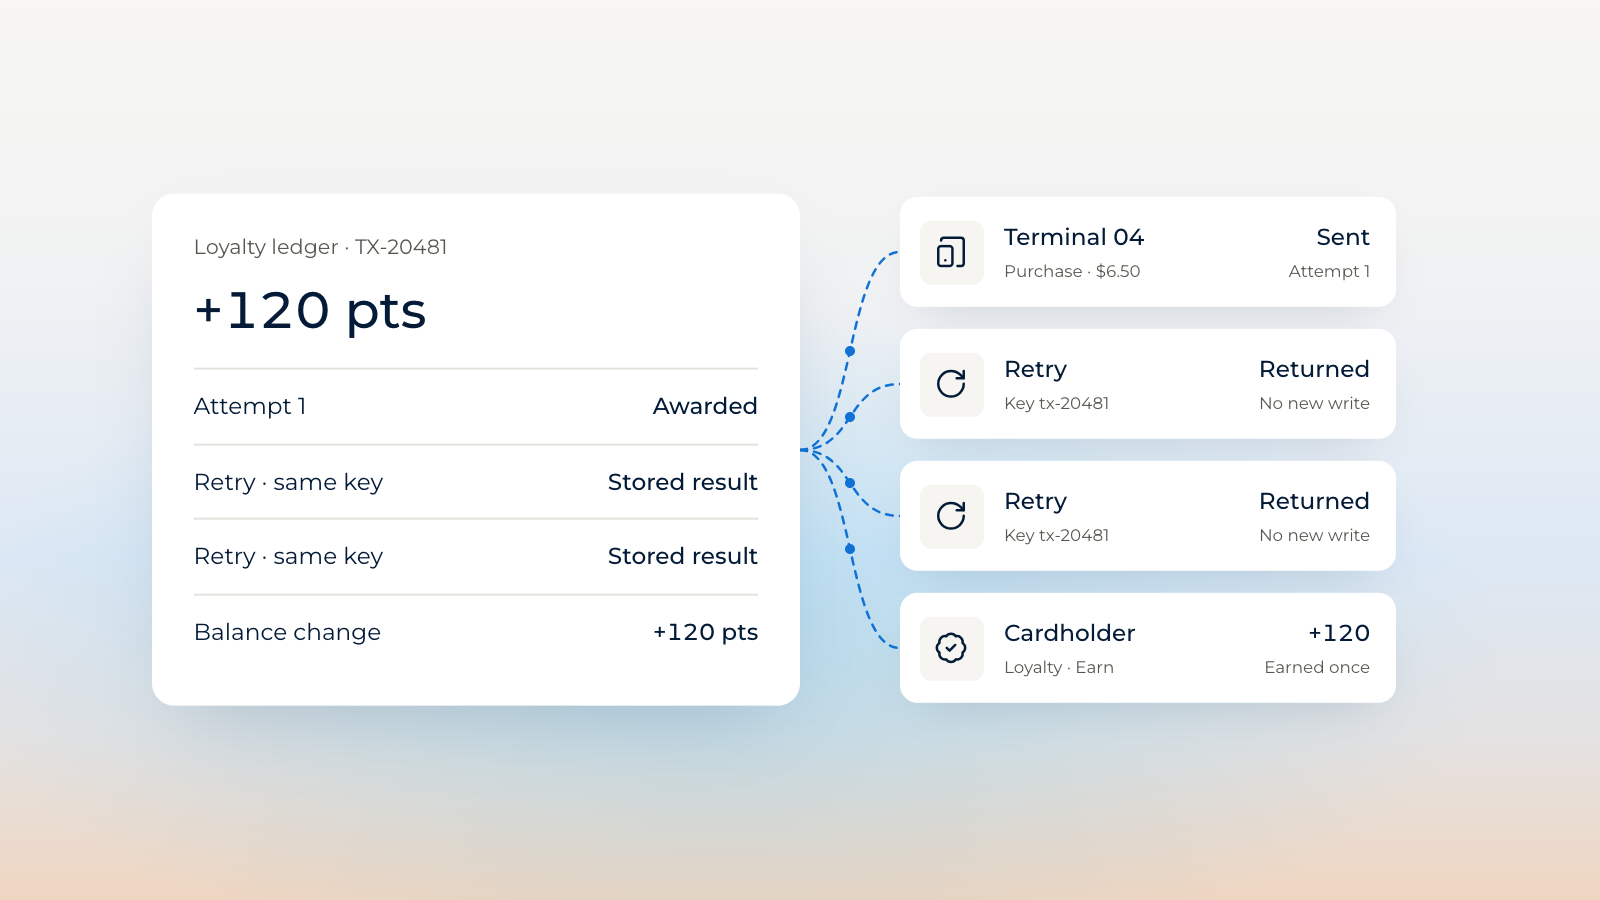
Agentic orchestration adds a coordination layer: understand the exception, evaluate the current state, check the allowed actions, select a response, execute within policy. Take an authorization timeout. Before retrying, an intelligent layer asks: was the request received? Has a delayed response arrived? Would a retry create a duplicate? Is another route available, and does policy allow it? Only then does it act.
Tokenization adds another layer
A token is not a static value. Its lifecycle runs from provisioning through activation, suspension, resumption, replacement, and deletion, and different systems participate at each stage. When a token is created but device binding fails, an orchestration layer can detect the partial state, evaluate recovery options, trigger a predefined compensating action, and escalate to a person if the situation exceeds its boundaries. AI does not control the token. It coordinates the journey around it.
Observability becomes more important, not less
For every important decision, operations teams should be able to reconstruct the chain: transaction, context, decision, capability, execution, result. Correlation IDs make that possible across processors, queues, databases, and tokenization systems. Agentic systems should not make payment infrastructure less observable. They should make the journey more explainable.
An architecture that keeps the controls
- Infrastructure layer — networks, issuers, acquirers, TSPs, processors, HSMs.
- Capability layer — authorization, risk, routing, tokenization, settlement.
- Agentic orchestration layer — context, state, decisioning, exceptions, recovery.
- Governance layer — policies, permissions, approvals, audit, observability.
- Experience layer — merchant apps, wallets, customer apps, operations consoles.
Multiple specialized agents — risk, routing, tokenization, reconciliation — may follow. But a central orchestration layer still has to govern permissions, state, and human approvals, or we trade one distributed systems problem for another: distributed decision-making without centralized governance.
Adaptive, not autonomous
The most useful future may not be fully autonomous payments. It is adaptive payment infrastructure — infrastructure that understands what is happening, what has already happened, what is allowed, and when a person needs to step in. That is very different from adding a chatbot to a payment app. Every retry, state transition, and permission matters, and every autonomous decision needs a boundary.
Where this lives at PayCloud
Payment Orchestration and HSM Orchestration are the capability and governance layers this model depends on — routing by business rules, with cryptographic operations that never leave the controls built around them.