Credit unions become the first card a member reaches for by being present before the habit forms and by giving the member a reason to choose them at checkout. That means getting the card into the member’s phone at approval, and connecting rewards to the payment itself rather than to a separate card.
What does top of wallet actually mean?
Top of wallet is the card someone reaches for without deciding.
The phrase comes from leather wallets, where one card sat in the front slot and got pulled out by reflex. The reflex is the point. Nobody weighs rewards structures at a coffee counter. They reach, and the card that comes out is the card that gets the transaction.
In a phone, the mechanism is different but the behavior is the same. A default card is chosen once, often during setup, and then almost never revisited. It opens when the phone is double-pressed at a reader. For a credit union, that default is worth more than any individual campaign, because it keeps earning without being re-won.
What drives top-of-wallet use?
Habit drives it, more reliably than any feature does, and that is a finding rather than an opinion.
Federal Reserve researchers looked directly at this. A 2026 Boston Fed working paper on merchant steering analyzed how consumers actually pay versus how they say they prefer to pay, and found that most of the time people use their preferred method for in-person purchases. It also identified inertia effects, meaning consumers are more likely to use the same payment method they used before.
That is the whole competitive picture in one sentence. You are not competing for a transaction. You are competing for a default that was set at some earlier moment and has been running on autopilot since.
The volume behind that default is substantial. The Federal Reserve’s 2026 Diary of Consumer Payment Choice found that consumers made an average of 47 payments per month, of which 16 were on a credit card and 15 on a debit card, with cards accounting for about two-thirds of all payments. A default that captures even part of that is an annuity. A card that never becomes the default is competing for whatever is left over.
Two implications follow for a credit union. First, early matters more than loud, because the default gets set before most marketing reaches the member. Second, a reason to choose has to exist at the moment of payment, not in a statement insert read three weeks later.
It is worth being precise about what the research does not say, because the honest version is more useful. It does not say members are loyal to a card. It says they repeat. Repetition is easier to earn than loyalty and easier to lose, and it belongs to whoever happened to be present when the pattern started rather than to whoever deserved it most.
How do credit unions add cards to Apple Pay and Google Wallet?
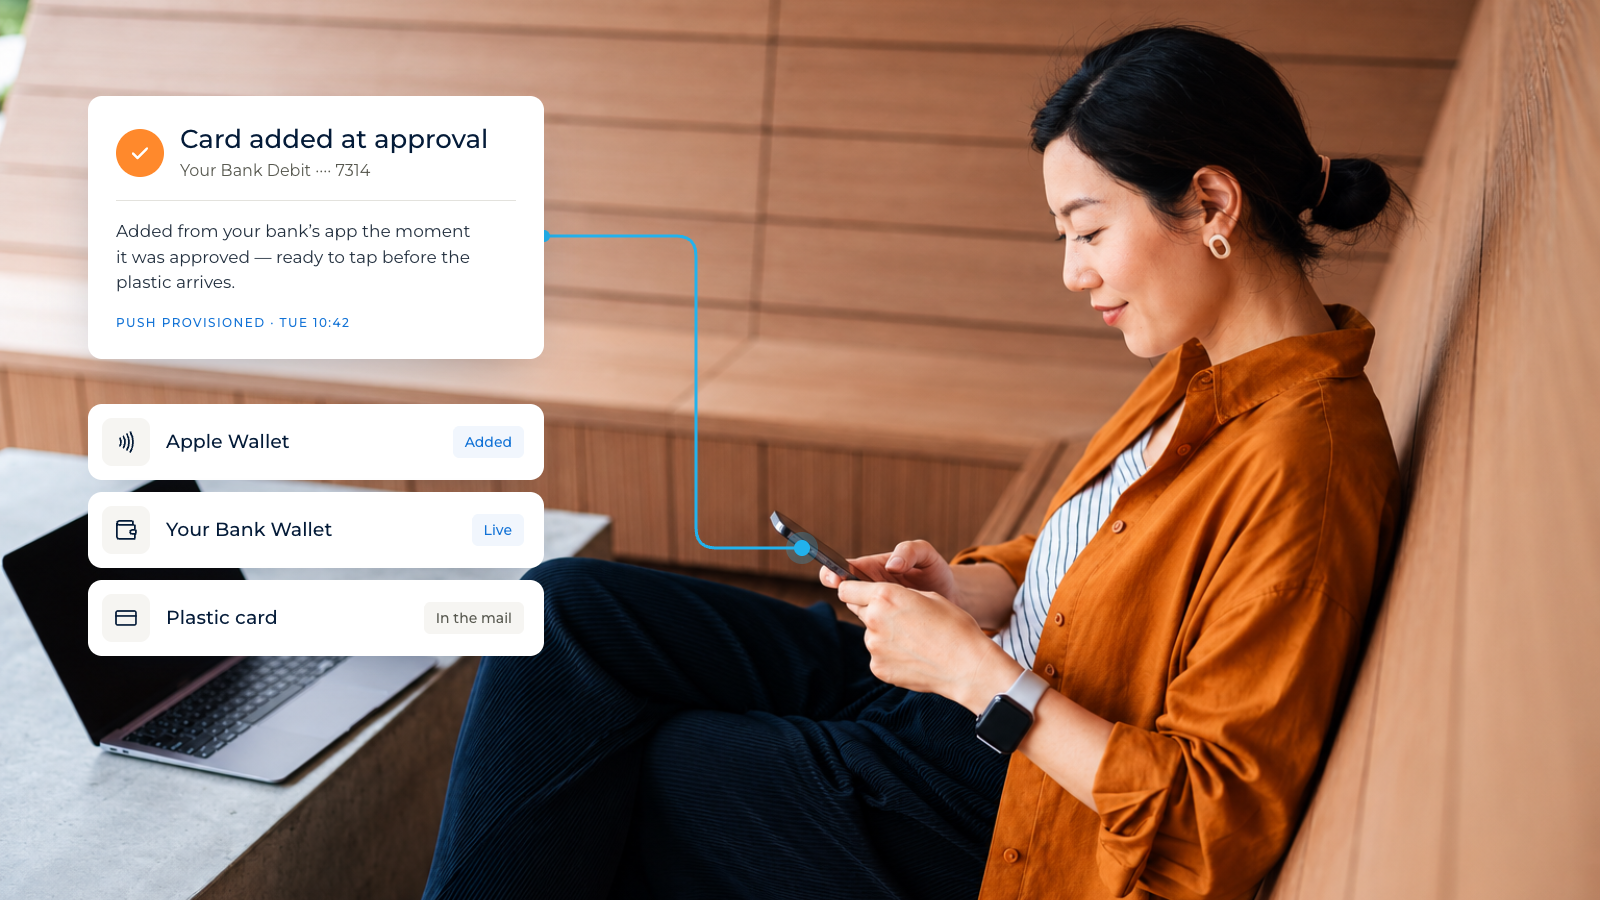
Through push provisioning, which lets a member add the card to the wallet directly from the credit union’s own app rather than typing a card number into it.
Both platforms publish issuer documentation and APIs for this, and the mechanics are the same for a credit union as for a national bank. The member taps a button inside your app, your systems verify that the person adding the card is the member, and the card data moves between systems rather than through a keyboard.
The verification step is where this succeeds or stalls, and it is largely your decision rather than the platform’s. A member who is already signed into your app has effectively authenticated. Sending them a one-time code and hoping it arrives adds a step that some fraction of them will not finish.
The strategic point is timing. Approval is when a new card has a member’s full attention, and it is also before any competing default has been reinforced one more time. A card that arrives by mail the following week is asking a member to change a habit. A card that arrives in the phone on approval day is asking them to form one.
There is a second effect worth planning for. A member who adds the card themselves, inside your app, with your name around the moment, knows where that card came from. Months later, when something looks wrong on a statement, that recognition is the difference between a quick call and a confused one. Provisioning is a service decision as much as a growth one.
Can loyalty run inside a credit union wallet?
Yes, through card-linked loyalty, where points are credited from the payment transaction itself rather than from a separate card the member has to remember to present.
Card-linked loyalty means the reward is attached to the payment credential. The member pays as they normally would, and the points are credited off the back of that transaction. There is no loyalty card to carry, no barcode to find, and no second step at the counter. Loyalty Exchange runs the points ledger for that, on the same platform as the payment.
This matters more for credit unions than for most issuers, because the member relationship is already the differentiator. A rewards program that requires a member to do extra work at a checkout is a rewards program most members will use inconsistently. One that credits automatically from a payment they were making anyway compounds quietly.
White Label Wallet is where those pieces sit together under the credit union’s own name: the card, the rewards balance, controls the member sets, and whatever credential comes next. The alternative is not that these things disappear. It is that they live in four places with four different brands on them, and only one of those brands is yours.
One caution on scope. Rewards that post automatically are not the same project as rewards that are generous, and the two get conflated in planning. The mechanism described here changes when and how reliably a member is credited. What they are credited remains an economics question your team owns, and no infrastructure decision will answer it for you.
What should a credit union decide first?
Decide whether your immediate problem is presence or reason, because they are solved in different orders and confusing them wastes a planning cycle.
Presence is a timing problem. If your card is not in members’ phones on approval day, that is the first thing to fix, and it is the smaller of the two projects. Reason is a loyalty and controls problem, and it is the larger one, because it involves deciding what you want to put in front of a member that a payment card alone cannot hold.
Most credit unions eventually need both. Very few need them simultaneously, and the institutions that try usually discover that the second project quietly set the timeline for the first. Sequencing them deliberately is the single cheapest decision available here, and it is made in a planning session rather than in a build.
Where to go next
White Label Wallet and Loyalty Exchange are part of PayCloud Provision™, built on Provision-Once Architecture™. A credential is provisioned once and managed through every change that follows, across payments, access, identity, and loyalty.
Related: How do banks put their own card in a customer’s phone the moment it is approved?
Provisioned once. Trusted everywhere. One secure infrastructure for payments, access, identity, and loyalty.
Frequently asked questions
How do credit unions add cards to Apple Pay and Google Wallet?
Through push provisioning, which lets a member add the card to the wallet directly from the credit union’s own app instead of typing in a card number. Both Apple and Google publish issuer documentation and APIs for it, and the mechanics are the same for a credit union as for a larger issuer.
Can loyalty run inside a credit union wallet?
Yes. Card-linked loyalty attaches the reward to the payment credential, so points are credited from the payment transaction itself rather than from a separate loyalty card. PayCloud’s Loyalty Exchange runs the points ledger on the same platform as the payment.
What drives top-of-wallet use?
Habit, more than features. Federal Reserve research finds that consumers mostly use their preferred payment method for in-person purchases and are more likely to repeat the method they used before. The practical consequence is that the default is set early and rarely revisited.
What is a credit union digital wallet?
A credit union digital wallet is a wallet app carrying the credit union’s own brand, holding the member’s card alongside rewards, controls, and other credentials. PayCloud’s White Label Wallet provides it, with the provisioning and key management infrastructure running underneath.
Should a credit union start with provisioning or with rewards?
Usually provisioning, because getting the card into members’ phones at approval is the smaller project and it addresses the moment when a payment default is set. Rewards and controls are the larger project and tend to set the overall timeline when both are attempted at once.
Sources
Federal Reserve Financial Services. 2026 Diary of Consumer Payment Choice, May 2026.